
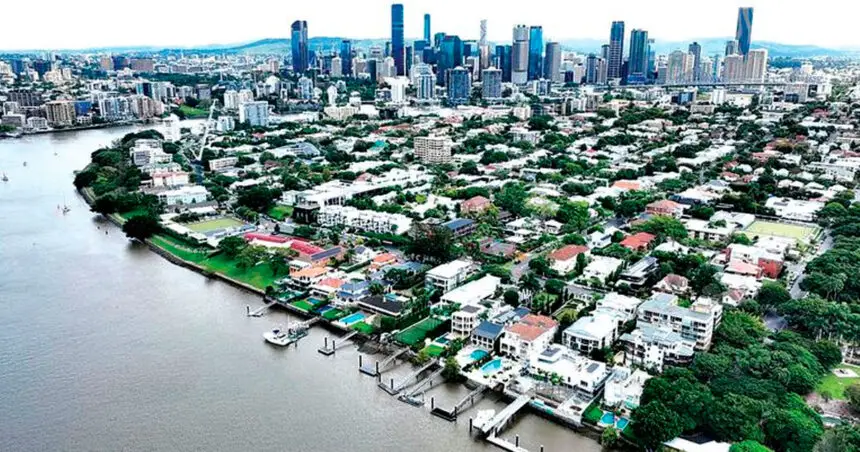
Realestate.com.au
BRISBANE’S property slowdown is delivering a painful reality check for some first-home buyers, with new research suggesting recent purchasers have seen as much as $225,000 wiped from the value of eligible properties in less than a year.
SuburbData research found more than half (54.1 per cent) of Brisbane homes eligible to be purchased with a five per cent deposit had lost equity since the Federal Government expanded its low-deposit scheme in October.
Almost one-in-four eligible properties had fallen by enough to wipe out the equivalent of the buyer’s entire five per cent deposit.
SuburbData director and property analyst Jeremy Sheppard said Brisbane could prove one of the riskier markets for first-home buyers in coming years if the downturn continued.
“The worst market to buy with a five per cent deposit is an area that is peaking, and that’s what’s happening in a lot of Brisbane,” Mr Sheppard said.
“There may still be growth in a lot of areas, but it would be a risky deal to buy in a lot of the Brisbane market right now.”
The research found 114 of the 223 Brisbane suburbs analysed had recorded negative equity growth among properties qualifying under the scheme.
Falls ranged from just 0.6 per cent through to 26 per cent, with the average eligible property losing about $55,960 in potential value.
The Cleveland-Stradbroke area recorded the biggest decline, with qualifying homes falling 26 per cent, representing a typical loss of $224,833.
Sunnybank followed with a 22 per cent decline, equivalent to about $191,754.
Higher borrowing costs have also changed the equation for buyers as Mr Sheppard said Australia’s three interest rate increases during 2026 had dented confidence.
“If rates go up, and certainly if it’s a sudden rise, the number of defaults increase … there will be more people in a tough situation,” he said.