
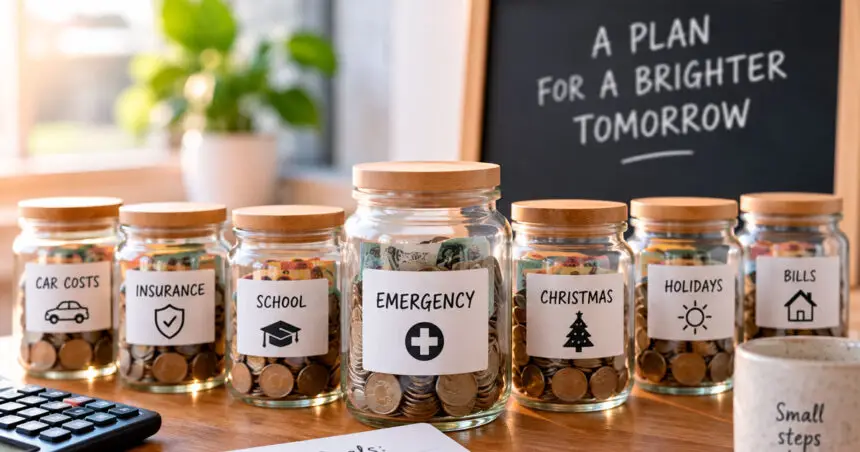
You finally get some money into savings and start to feel like you are making progress. Then the car registration arrives, insurance is due, the kids need something for school, Christmas approaches, or the car needs a service.
Before long, the savings account has taken another hit, and it feels as though you are back where you started. The frustration can make it seem as though saving simply does not work, even when you have been putting money aside consistently.
The real issue may be that the same pool of money is being asked to cover too many different expenses.
NOT EVERY EXPENSE IS UNEXPECTED
Some expenses genuinely arrive without warning. An urgent home repair, an unexpected medical cost or a sudden loss of income can create genuine financial pressure and are exactly the types of situations emergency savings are designed to help with.
Many household expenses, however, can be anticipated well in advance. Car registration, insurance renewals, school costs, Christmas, council rates, memberships and annual subscriptions all show up on a predictable cycle.
You may not know the exact amount months ahead, but you usually know the expense is coming.
GIVE YOUR SAVINGS DIFFERENT JOBS
A simple way to create more clarity is to separate your savings into different categories or savings buckets. These could include emergency savings, car costs, annual bills, Christmas, holidays, school expenses and other known commitments.
The purpose is to understand how much of your savings is genuinely available and how much has already been allocated to a future expense. Once those amounts are separated mentally or physically, it becomes much easier to see your true financial position.
This also helps protect your emergency fund. If emergency savings are continually used for annual insurance, registration, or Christmas, that money is never available for the situations it was originally intended to cover.
TURN LARGE BILLS INTO SMALLER, REGULAR AMOUNTS
Once you know an expense is coming, work backwards and convert it into a regular amount. If your household typically spends $2000 at Christmas, that is around $167 per month or $77 per fortnight.
If your annual insurance premium is $1200, setting aside $100 each month means the money is ready when the renewal arrives. The bill has not changed, but you have prepared gradually instead of finding an amount at short notice.
Knowing the money is there also reduces stress. Opening a bill feels very different when you have made room for it in your plan.
If multiple categories feel too complex, start with an emergency fund.